Lawrence W. Abrams
Ph.D. Economist
Email me at [email protected] for zoom chats on PBM, vernacular market designs in AI ecosystem
I have a B.A. in Economics from Amherst College and a Ph.D in Economics from Washington University in St. Louis. My writings are at the intersection of economics, accounting, financial
analysis, and high tech. I have received no remuneration for these articles and have no financial relation with any company discussed in these articles
Scroll Down for Papers - .pdf dowloadable for free
A Combinatorial Auction Design for Formulary Positions
April 2, 2025, 29 pages
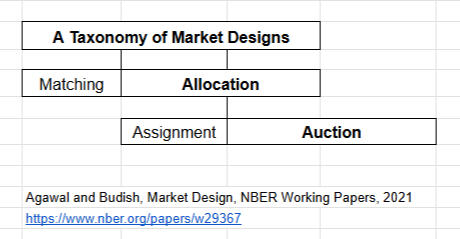
The Wyden-Grassley 2019 Senate Staff Report confirms that rebate contracts between
pharmaceutical companies (Pharma) and the Big 3 pharmacy benefit managers (PBMs)
contain a combinatorial bid-menu for formulary positions featuring both exclusive and
shared positions. Pharma bid-menus often include a separate bid option for “an
incremental base rate” if the PBM outright excludes a named competing drug. The
standard bid basis is a percentage off a publicly available list price.
The purpose of this paper is to apply the economics field of market design to develop a
simple algebraic and graphic model of a combinatorial auction for formulary position
assignments.
This paper is evidence of economist Ran Spiegler’s observation in his book The Curious
Culture of Economic Theory that market design economics blurs the lines between an
economist and the market designer. In places, this economist becomes a market
designer suggesting the following ways PBMs can improve their auction design:
1. a test for anticompetitive incremental exclusionary rebate bids.
2. a more incentive-compatible auction by limiting shared position bid-downs.
3. banning lump sum, bundled, market share, and all other non-linear rebate bid
bases.
A Market Design Framework for Antitrust Causation in the Google Search Case, August 12, 2025, 9 pages
Abstract
On August 5, 2024, U.S. District Court for the District of Columbia Judge Amit P. Mehta ruled that Google violated Section 2 of the Sherman Act by maintaining a monopoly in general search services. Google achieved and maintained its monopoly via a series of exclusive deals spanning two decades with Apple Computer and other device manufacturers.In this article, we apply market design economics to develop a “but-for” standard for the causal link between Google’s anticompetitive bidding for search engine contracts and harm to rivals and consumers. Our market design model locates anticompetitive conduct in Google’s repeated no-bids for shared choice screen contracts. Specifically, we argue that Google’s repeated no-bids in 2007, 2009, and 2012 were equivalent to grossly overestimated and anticompetitive liquidated damage clauses in exclusive contract offers.One takeaway from this paper is that it is problematic for a dominant supplier to have the record show a no-bid on a shared position contract offer while making a multi-Billion dollar bid on an exclusive position contract offer.JEL Classification: D44, D47, K00, K21, L40, L42, L49, L86
Clarifying Trinko as Precedent in EHR and AI Memory Duty to Deal Cases: A New Institutional Economics Approach, November 25, 2025 , 7 Pages
Abstract
By clarifying the bases for SCOTUS' opinion in Verizon Communications Inc. v. Law Offices of Curtis V. Trinko, LLP, (2004) ( Trinko), we hope to reduce two distinct errors. The false positive error is citing Trinko as precedent when it isn't. This error is so prevalent it has earned the nickname of "Trinko Creep." The false negative error is not citing Trinko when it should be. We argue that this error will be growing in the future as Trinko should be precedent in cases involving regulated access rights to sensitive consumer data in electronic health records (EHRs) and and Agentic AI Long Term Memory (AI-LTM).Keywords: Trinko, New Industrial Economics, Polycentric Goverance, Verizon V. Trinko, Unilateral Duty to Deal Cases, Antitrust, Property RightsJEL Classification: K11, K12, K21, L51, L86, I11, D86, D23
The Jump Scare: Life Lessons from Five Nights at Freddy’s Game
Life in front of a monitor occasionally involves what gamers call the “jump scare.” There are life lessons to be learned with how to deal with "jump scares".
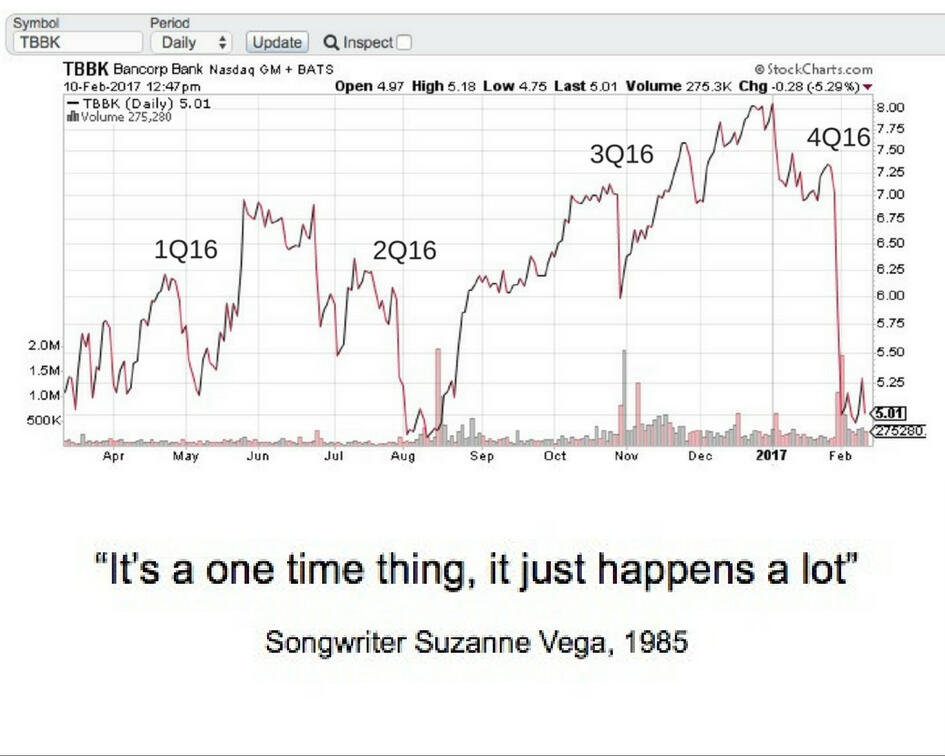
The Bancorp: A Test for Post-Enron GAAP, 16 pages, September 12, 2016
Abstract
The purpose of this paper is to review a late 2014 non-consolidation decision of The Bancorp (NASDAQ:TBBK), a Philadelphia area bank with a diversified loan portfolio, but also known for being one of largest issuers of reloadable prepaid debit and gift cards in the country.Based on detail presented below, we conclude that either that The Bancorp is not in compliance with Post-Enron GAAP and or that it has been so watered down as to weaken the effectiveness of the Dodd-Frank Act in ensuring that banks are well capitalized.Generally accepted accounting principles (GAAP) relating to consolidation of subsidiaries have changed dramatically in response to the Enron scandal of the late 90s. Pre-Enron, GAAP for consolidation was specified in ARB No. 51.Post-Enron in 2003, the Financial Accounting Standards Board (FASB) issued FIN 46 - an interpretation ARB No. 51. The simple majority interest rule was complete scraped. Instead, FASB said that an enterprise must consolidate a variable interest entity (VIE) ― variable shares of equity and debt ― when it had a controlling financial interest as defined quantitatively by the obligation to absorb the major share of losses or the right to receive the major share of benefits.In 2009, FASB amended FIN 46(R) to take into account the valid criticism from lenders to VIEs who had to consolidate because they had a majority financial interest but absolute no power to direct the activities that affected the financials.This amendment ― FASB 46(R) - Statement 167 ― added a qualitative stipulation that a corporation must consolidate a VIE if it had most of the power to direct the activities as well as a majority interest in the resulting financial gains and losses.Majority financial interest can be determined quantitatively and has been relatively easy to evaluate for compliance. But, as PwC lamented in a bulletin, the qualitative question of who has the most decision-making power “will require considerable judgment.”Keywords: GAAP, Enron Scandal, GAAP for Consolidation of VIE, the Bancorp, Dodd-Frank, Well-Capitalized Bank, FASB Fin 46, FASB 46(R), Statement 167JEL Classification: M41, M48, G28, G21
Quantifying the Requirements to Scale a Carpooling Business, 21 pages, July 8, 2017
Abstract
Carpooling is now seen as last big opportunity to grow a shared mobility as a service (MaaS) business ahead of the arrival of autonomous vehicles (AVs).We present the case that Waze’s altruistic vision of carpooling is insufficient to scale the business.Our transactional vision of the business, requiring market pay rates to drivers, creates little incentive for people to choose carpooling over solo commuting.We think that it will take a minimum of $4,000 in cost saving to motive a significant number of people to go carless. This implies that fares will have be reduced by an additional $1,583 a year to reach that level of cost savings.The way to recoup this is by negotiating referral credits (dollar or accounting) with related units offering last-mile ride-sharing, delivery, and weekend car rentals.Keywords: carpooling, congestion pricing, Mobility-as-a-Service, MaaS, Waze, Uber, Lyft, Ford Smart Mobility, HOV lanes, ride-hailing, carpooling, reverse commutersJEL Classification: R40, R41, R48, H23, L81, L86, L87, L91, L92